Back to all companies
Sign in
Back to all companies
LendUp logo

LendUp

Winter 2012Inactive

LendUp is a socially responsible company on a mission to redefine…

Save
LendUp logo

LendUp

Winter 2012Inactive

LendUp is a socially responsible company on a mission to redefine…

Save
Company details

Could a fintech company be built that helps people today, and prepares them for tomorrow? One that offers consumers high quality, mobile-first credit and savings products and protects them from tricks and traps? That’s LendUp. LendUp's mission is to provide anyone with a better path to financial health.

We believe there are two types of financial products: chutes and ladders. Ladders help people up, chutes push people down. One of our core values is that every product we offer at LendUp is a ladder, measured by the long-term financial well-being of our customers. LendUp credit cards, loans, and savings resources reflect our commitment to getting our customers to a better financial state.

We are a data-driven company and build all of our technology in-house. With a firm belief that you're more than your credit score, we're extending credit as aggressively as possible and helping solve for the income volatility and financial instability that affects more than 140 million Americans.

We are backed by more than $325 million in debt and equity financing from investors such as GV, PayPal, Y Combinator, QED Investors, Susa Ventures, Data Collective, Thomvest Ventures, Kleiner Perkins, Kapor Capital, Bronze Investments, radicle impact, Victory Park Capital, Reddit co-founder Alexis Ohanian, Gmail founder Paul Buchheit, Troy Carter, and many others.

One of our values is "different backgrounds, same mission."​ We come from venerable Silicon Valley technology companies, major banks, nonprofits and law firms. We're former consumer advocates, regulators and academics. Together, we're bringing our mission to life. Join us!

Location
San Francisco, CA, USA
Founded
2011
Category
Fintech
YC profilelendup.com
Founders
  • SO
    Sasha Orloff
    Founder/CEO
    X / TwitterLinkedIn
  • JR
    Jacob Rosenberg
    Founder/CTO
    LinkedIn

Pressure-test this opportunity

Explore the risks and possibilities with a prompt for ChatGPT, Claude, or your agent.

On this page
  • Overview
  • Founding Story
  • Timeline
  • What They Built
  • Market Position
  • Business Model
  • Post-Mortem
  • The advertised path exceeded the delivered product
  • Repeated enforcement removed the ability to lend
  • Key Lessons
  • Sources

AI-researched. Check the sources before making a decision.

Found a mistake? Let @oscrhong know.

Startups.RIP — Good ideas. Better timing.
PricingContactPrivacyGot feedback? DM @oscrhong
Build it!

LendUp (W12) at a glance

  1. Make promised progress measurable. The Ladder depended on better terms and reporting. Check delivered benefits for each eligible borrower before repeating the marketing claim.
  2. Keep geography inside the promise. Higher tiers were largely limited to California. A nationally visible progression story needs state-specific availability, not just a working feature somewhere.
  3. Separate volume from economics. LendUp reported billions in originations and substantial mixed financing. Principal advanced and money raised do not establish profitable lending or improved customer outcomes.
  4. Track the assets after a split. Mission Lane inherited cards, technology and people. Its continuing business deserves separate assessment from the lender barred from new credit.

Overview

LendUp sold short-term credit with a promise of progress. Borrowers could earn Ladder points through repayment and education, then qualify for better terms. That promise gave the online lender a clear identity among payday alternatives. Its delivery failures also became the center of repeated enforcement. The court barred new lending in December 2021. [1]

The history has several separate outcomes. LendUp's card business became Mission Lane in 2019. Today's LendUp.com describes different ownership and a loan-matching business, with no corporate relationship to the former lender. Neither establishes that the original loan operation survived its enforcement order. [2] [3]
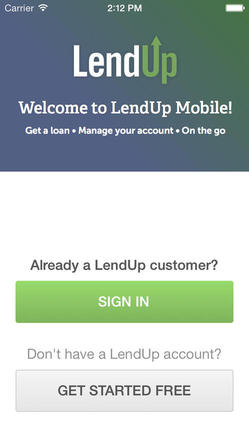
LendUp Mobile welcome screen with sign-in and account creation buttons
Finovate's November 2013 coverage showed this mobile welcome screen. Existing borrowers could sign in; new customers could start an application.
Two LendUp presenters on the FinovateSpring stage
Finovate TV's 2014 demonstration. The organizer names Sasha Orloff and Jacob Rosenberg as presenters of the lending platform.

Image 1 / 2

Founding Story

Stepbrothers Sasha Orloff and Jacob Rosenberg started the company in 2011. In a 2018 interview, Orloff described its operational beginning after YC's Winter 2012 batch. He and policy executive Jotaka Eaddy framed the customer problem as volatile income and poor access to conventional credit. Their ambition extended beyond emergency loans into cards, savings and education. [4]

YC's current directory identifies Orloff as former CEO and Rosenberg as former CTO, and marks LendUp inactive. The historical company description says it built its technology internally. That ownership made product behavior central to its responsibility: the promises depended on reporting, pricing and eligibility systems actually working. [5]

Orloff also explained the founding pitch publicly at TEDxSacramento. The talk documents his proposed alternative to payday lending; it does not establish delivered borrower benefits.

Disrupting payday loans: Sasha Orloff at TEDxSacramento, published by TEDx Talks

Timeline

  • 2011–2012: Founding followed by YC Winter 2012 and the start of lending. [4]
  • 2013: FinovateSpring Best of Show; an iPhone app followed in November. [6]
  • 2014: A Finovate demonstration promoted partner access through a lending API. [7]
  • September 2016: The CFPB ordered refunds, a penalty and corrections to misleading loan marketing and disclosures. [8]
  • March–June 2017: LendUp announced a $100 million credit facility and later an undisclosed PayPal investment. [9] [10]
  • January 2019: The card portfolio, technology, intellectual property and team separated into Mission Lane. Anu Shultes became LendUp CEO. [2]
  • December 2020–January 2021: A Military Lending Act lawsuit was followed by a proposed settlement. [11]
  • May–June 2021: Related executive-led Ahead Financials promoted its digital financial platform through culture, gaming and music partnerships. [12] [13]
  • September–December 2021: The CFPB sued over alleged repeated Ladder misrepresentations. A proposed resolution on December 21 became a court order on December 30. [14] [1]
  • May 2024: The CFPB announced $39,833,748.87 in victim-fund payments for 118,101 affected consumers. [15]

What They Built

The Ladder combined short-term loans, repayment history and free courses. The advertised progression included lower rates, larger amounts and credit reporting at higher levels. These were consequential product benefits: a borrower could choose an expensive initial loan partly because of the promised future improvement. [16]

The 2013 iPhone app brought applications and account access onto mobile devices. Finovate described initial loans up to $250 and larger amounts for returning customers, with rapid deposits at participating banks. Those were contemporary product claims, not universal availability or timing guarantees. The 2014 API pitch extended distribution to financial institutions, merchants and community organizations. It demonstrated an integration strategy; the surviving demo profile does not establish how many partners adopted it. [6] [7]

Cards were a distinct product line. The 2019 separation announcement identifies both the Arrow Card and L Card, with Vijesh Iyer leading the new Mission Lane and Rosenberg moving with its technology team. The announced rationale was separate platforms and capital structures. That gives a concrete organizational explanation, without proving that investors abandoned the remaining lender. [2]

Market Position

LendUp positioned itself against payday lending through an online experience and a route toward better terms. In 2018, Eaddy said 98% of customers arrived on mobile phones. The interview also describes Finance Forward, an Aspen-linked effort connecting employers, nonprofits and financial institutions around income volatility. These show a distribution and policy strategy beyond an application form. Acquisition cost and conversion results remain unavailable. [4]

Ahead Financials later tested cultural distribution under Shultes and Kimberly Morgan. Its May 2021 announcement described Ahead for All: Iddris Sandu's AR experience, a Marvin Bing/Fairfax Studios documentary series, Spawn on Me gaming, Music BREAKr playlists and a fashion capsule. Named collaborators included Coco + Breezy, Lauren Halsey and Distortedd. A Los Angeles pop-up directed proceeds to Gameheads, Summa Everythang and Streetcode Academy. The announcement said the app was available while preparing for a summer launch. [12]

A June announcement added a BREAKr/Rolling Loud contest to put an emerging artist on the Miami stage, with Collab Crib involved. These are documented audience-building efforts; they do not prove profitable banking acquisition. [13]

Beam's March 2023 executive announcement says Morgan co-founded Ahead and that it was acquired, without naming the buyer. Greenwood announced its acquisition of Kinly in May 2023. The reviewed primary sources do not establish the complete Ahead-to-Kinly asset transfer, so its terms and customer continuity remain unresolved. [18] [19]

As checked in October 2026, Mission Lane still offers credit cards, including a Silver Line product advertising no annual fee and access to a TransUnion score. The separate operator of LendUp.com offers loan matching. A rebuild cannot assume the card market disappeared when the original lender stopped. [17] [3]

Business Model

LendUp earned lending income from loans and operated a separate card business before the split. Funding supplied both company capital and money for lending. Its March 2017 announcement put cumulative financing at $325 million in debt and equity, including a $100 million Victory Park Capital credit facility. It reported 3.3 million loans and over $1 billion in cumulative originations. Originations measure principal advanced, not revenue, profit or distinct borrowers. [9]

PayPal's investment announcement also named compliance and finance hires, including Mandeep Walia as chief compliance officer. Investment and senior hiring demonstrate support and organizational activity; they do not independently verify controls or customer outcomes. [10]

Orloff's current YC biography says LendUp and Mission Lane each grew past $100 million ARR. This is a founder claim without audited financials in the reviewed record. The evidence establishes lending volume and access to capital more clearly than durable unit economics, loan-loss rates or acquisition efficiency. [5]

Post-Mortem

The advertised path exceeded the delivered product

The 2016 CFPB action concerned several concrete mismatches. Higher-tier products were generally available only in California, despite broader marketing. Loan information was not furnished to credit-reporting companies until at least February 2014. The agency also identified undisclosed reversals of early-repayment discounts and incorrectly treated portions of expedited fees in disclosures. Its order required $1.83 million in refunds and a $1.8 million penalty, alongside operational changes. [8]

The important product boundary was eligibility as well as reporting. A national progression story could exceed what a borrower in a particular state could access. The consent order's findings connect the marketed benefit to missing delivery. That supports an operational diagnosis without claiming to know executives' motives. [16]

Repeated enforcement removed the ability to lend

In September 2021, the CFPB alleged that 140,000 repeat borrowers received the same or higher rates after ascending the Ladder. It separately alleged late adverse-action notices for over 7,400 applicants and inaccurate principal denial reasons in over 71,800 notices. Those notice claims concerned the Equal Credit Opportunity Act and Regulation B. They were allegations in the complaint, rather than a published trial finding or admission. [14]

The separate military-lending complaint concerned over 4,000 loans to more than 1,200 covered borrowers. Its January 2021 proposed settlement specified $300,000 in redress and a $950,000 penalty. The relevant cap was the Military Annual Percentage Rate, which includes specified charges and is not interchangeable with an ordinary advertised APR. [11]

The December 30 order barred new credit and assistance to others providing it, and restricted collection or transfer of defined subject loans. It imposed a $100,000 penalty. A $40.5 million redress obligation was suspended upon penalty payment because of demonstrated inability to pay. The later victim-fund distribution was separate: the CFPB announced nearly $40 million for affected consumers in May 2024. [1] [15]

Y

Regulators Shut Down Lending Platform (YC Alum) LendUp

669 points646 comments

The order explains why the historical lender could no longer pursue its core business. Public evidence does not isolate internal remediation decisions, lifetime economics or a complete asset-disposition chain for Ahead. The surviving card company and reused domain must be assessed separately from that outcome.

Key Lessons

  • Make progression observable. A point balance is weak evidence of improvement. Compare promised terms with actual borrower eligibility, offers and completed reporting.
  • Treat state availability as part of the product. A feature can exist in one market while making the nationwide pitch misleading.
  • Carry evidence across a split. Mission Lane inherited specific assets and people. Evaluate each resulting business on its own operations and outcomes.
  • Measure distribution separately from delivery. Mobile access, cultural campaigns and investor support can bring attention. They do not demonstrate the benefit sold to the customer.

Sources

  1. CFPB Spring 2022 report: entered judgment and financial terms
  2. LendUp: Mission Lane separation announcement, January 2019
  3. Current LendUp operator: ownership and loan-matching disclosures
  4. Financial Revolutionist: Orloff and Eaddy interview, March 2018
  5. YC company and founder profiles
  6. Finovate: iPhone application launch, November 2013
  7. Finovate: 2014 platform demonstration
  8. CFPB: 2016 enforcement action
  9. LendUp: 2017 credit facility and cumulative originations
  10. LendUp: PayPal investment and executive hires
  11. CFPB: military-lending proposed settlement
  12. Ahead Financials: Ahead for All campaign
  13. BREAKr: Rolling Loud and Ahead contest
  14. CFPB: September 2021 complaint announcement
  15. CFPB: May 2024 victim-fund distribution
  16. CFPB: 2016 consent order
  17. Mission Lane: current Silver Line credit card
  18. Beam: Kimberly Morgan appointment and Ahead acquisition reference
  19. Greenwood: Kinly acquisition announcement, May 2023