Overview
BlockFi offered cryptocurrency holders familiar financial services: borrowing, trading, and accounts paying interest. Zac Prince and Flori Marquez founded the New Jersey company in 2017. It raised a $350 million Series D at a $3 billion valuation in March 2021.[1]
The company entered Chapter 11 on November 28, 2022. Its platform later closed, while its estate pursued recoveries from failed counterparties. The case shows how an accessible financial product can conceal a difficult credit business. It also shows why recovering a dollar-denominated bankruptcy claim differs from returning the original quantity of cryptocurrency.[5][7][9]
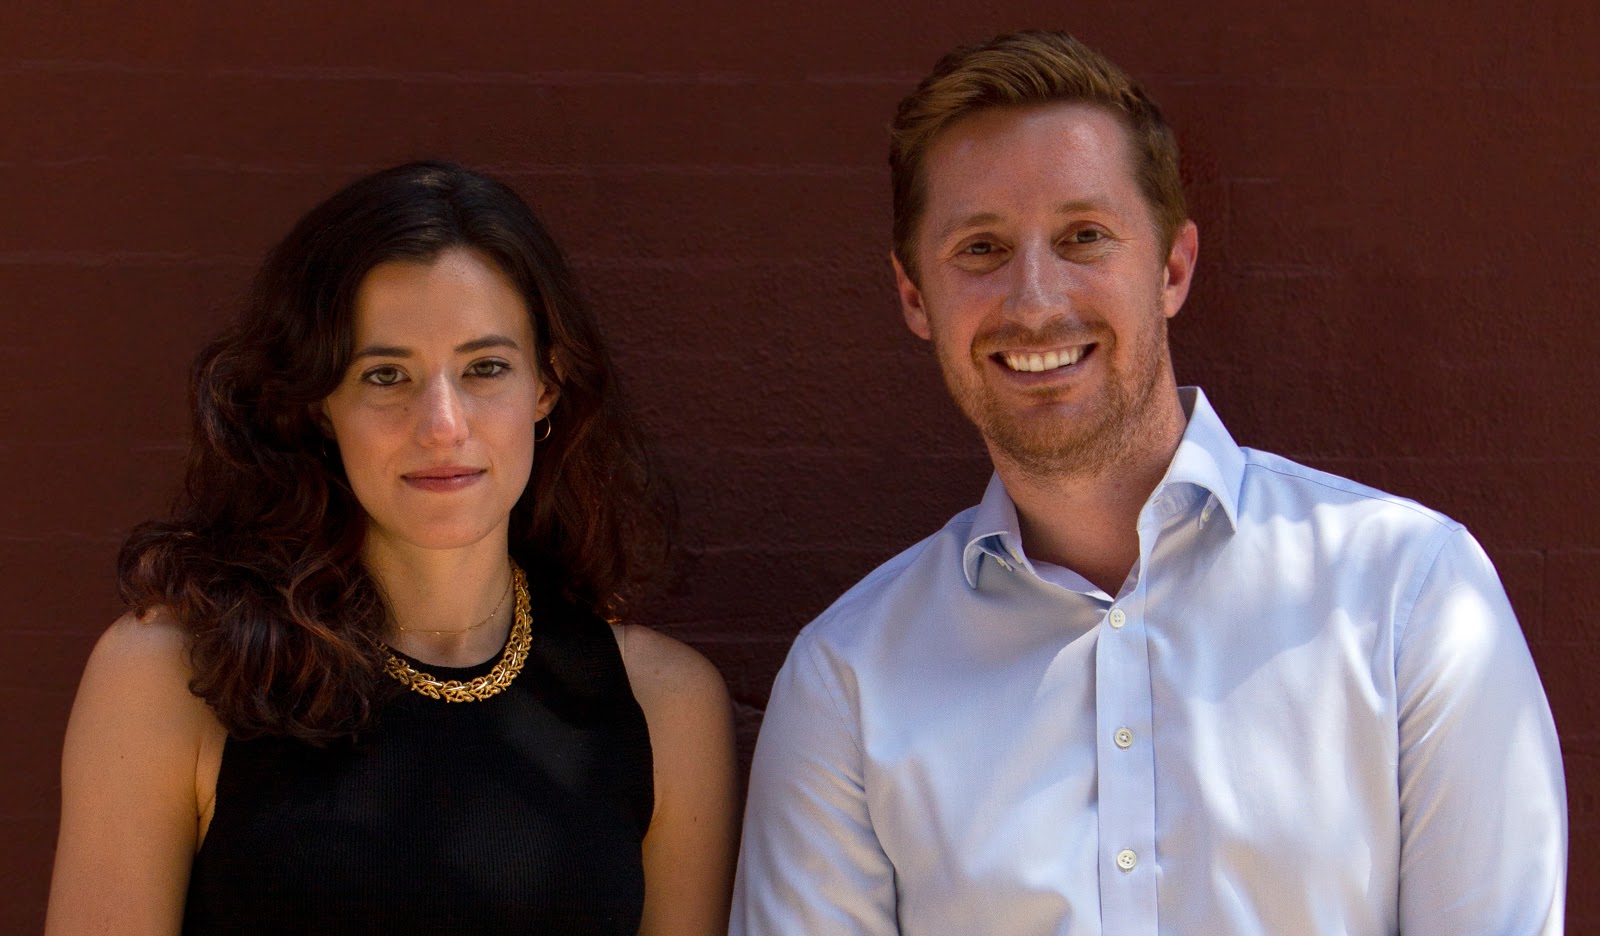
Image 1 / 1
Founding Story
Prince worked at Admeld before its acquisition by Google, then led business-development teams at Orchard Platform and Zibby. In his SALT interview, he described discovering Bitcoin while writing about financial technology. Growing attendance at New York cryptocurrency meetups suggested a market for financing digital assets. His earlier credit experience shaped the opportunity he saw.[2]
Marquez described the company's goal as helping “facilitate cryptocurrencies going mainstream.” The proposition connected assets people already held with financial services they understood. It avoided requiring customers to master a new financial interface before they could borrow or earn interest.[1]
The reviewed sources do not establish how Prince and Marquez first met or decided to work together.
The parent formed in 2017; BlockFi Lending LLC formed in 2018. The subsidiary was the respondent in the SEC proceeding.[4]
Timeline
- 2017: Prince and Marquez founded BlockFi.[1]
- January 2018: BlockFi made its first loan, according to Prince's later interview.[2]
- March 4, 2019: BlockFi began publicly offering its interest accounts.[4]
- March 2021: Its Series D raised $350 million.[1]
- February 2022: BlockFi agreed to a $100 million settlement with the SEC and state regulators.[3]
- June 30, 2022: It entered an FTX US loan agreement with an acquisition option.[5]
- November 10, 2022: It announced a pause in withdrawals.[6]
- November 28, 2022: BlockFi and affiliated debtors filed Chapter 11 petitions.[5]
- July 2024: The administrator completed a sale of FTX claims and announced capacity for full allowed customer-claim distributions.[9]
What They Built
The retail offering combined cryptocurrency-backed loans, trading, interest accounts, and a Bitcoin rewards credit card. The institutional side financed trading firms and other market participants. Prince described a single platform joining these activities rather than a standalone wallet.[2]
Interest-account customers lent assets to BlockFi for variable interest. BlockFi deployed them through loans and investments. Repayment depended on the company's financial management.[4]
In July 2021, Prince told SALT, “It's absolutely safe and secure.” He cited custody and risk management. This historical assurance did not establish protection against credit losses.[2]
Market Position
Target Customers
Retail customers wanted to hold cryptocurrency while obtaining cash or earning interest. Institutional customers needed financing and trading services. Those groups met through BlockFi's balance sheet, even when the retail experience made the product feel simple.[2]
Market Size
BlockFi's March 2021 release claimed more than 225,000 clients, over $15 billion on its platform, and monthly revenue above $50 million. These figures describe the company at that date. Platform assets were distinct from company revenue, valuation, or equity funding. They also changed with asset prices and customer activity.[1]
The SEC recorded approximately $10.4 billion in interest-account assets and 572,160 investors on December 8, 2021. This product-specific count differs from the earlier company client count.[4]
Competition
Customers could retain assets without lending them, use other lenders, or sell assets for cash. Institutional demand supplied an opportunity, but also concentrated exposure within the same young financial market. A better advertised rate did not settle the question of borrower quality or withdrawal reliability.
Business Model
Prince explained that BlockFi could pay interest because it charged borrowers for capital. The spread between those activities supported the business, alongside its other services. This was credit intermediation: the company accepted repayment obligations while taking exposure to borrowers and investments.[2]
The SEC's settled order found misleading collateral statements. Approximately 24% of institutional cryptocurrency loans in 2019, 16% in 2020, and 17% through June 2021 were over-collateralized. BlockFi accepted the order without admitting or denying its findings.[4]
The $100 million regulatory settlement comprised $50 million to the SEC and $50 million to states. It was a penalty agreement, distinct from venture funding or money returned to customers. The intended registration of a new interest product did not establish that regulators had approved it.[3]
Outcome and evolution
The debtor adviser's first-day declaration describes losses and withdrawals before the FTX failure. FTX US then offered borrowing capacity of up to $400 million and an option to acquire BlockFi. The declaration reported approximately $275 million outstanding at filing. A credit limit, drawn debt, and an acquisition option describe different financial facts.[5]
That support created another dependency. The same declaration described loans to Alameda and assets trapped on FTX. California's regulator recorded BlockFi's November 10 withdrawal pause amid uncertainty about FTX and Alameda. The Chapter 11 filing followed on November 28. The adviser's account explains the debtor's position; it is not a court finding that every earlier risk decision was sound.[5][6]
The estate's March 2024 FTX settlement announcement distinguished a $689.3 million Alameda claim from a $185.2 million FTX.com customer claim. Those claims concerned different exposures. The July administrator release then reported their sale above face value, enabling a final distribution of 100% on allowed customer and general unsecured claims.[8][9]
The denominator matters. The estate's FAQ valued interest-account claims in US dollars at bankruptcy, including applicable interest. A full recovery of that allowed claim did not promise the original coin quantity or its later market value. The July announcement described distribution capacity and plans, rather than proving that every eligible person had received payment.[7][9]
An April 2025 notice still addressed international business accounts with outstanding distributions and verification requirements. The current domain remains an estate information site. This review establishes neither universal completed payment nor the resolution of every legal dispute. The original lending platform remains inactive.[10][9]
Key Lessons
- BlockFi Interest Accounts made earning interest accessible while customers lent assets to the company. Their repayment depended on BlockFi's borrowers and investments.
- FTX US offered BlockFi rescue financing while BlockFi also had Alameda loans and assets on FTX. Connected counterparties made the rescue another source of exposure.
- The SEC found that BlockFi's institutional-loan collateral statements were misleading. Secure custody and a planned registration could not establish the loans' collateral coverage.
- BlockFi's announced full recovery applied to allowed dollar claims valued at bankruptcy. That measure differed from original cryptocurrency quantities, later appreciation, and universal completed payment.
Sources
- BlockFi completes Series D — 2021-03-11.
- Zac Prince at SALT — 2021-07-06.
- SEC charges BlockFi Lending — 2022-02-14.
- SEC administrative order — 2022-02-14.
- Renzi first-day declaration — 2022-11-28.
- California withdrawal pause notice — 2022-11-11.
- Estate distribution FAQ — 2024-03-01.
- FTX litigation resolution — 2024-03-07.
- Claims sale and customer recovery — 2024-07-22.
- International business account remediation — 2025-04-16.
- Rotki: Current pricing — accessed 2026-10-23.
- Koinly: Current pricing — accessed 2026-10-23.