Overview
Frubana made buying food easier for independent restaurants by combining an ordering app with distribution. It later added supplier advertising and financial services. Founded in Colombia in 2018, the company joined Y Combinator's Winter 2019 batch. Its last delivery in Brazil was July 30, 2025, following exits from Colombia and Mexico in February 2024. The approximately $271 million reported raised is funding, not a measure of losses. [1][8]
Its trajectory shows the gap between a useful purchasing service and a business able to finance that service. Frubana could improve a warehouse process, attract repeat purchases, and offer credit while still needing capital to keep operating. The clearest documented failure mechanism is financing dependence during retrenchment. Public evidence does not isolate how much came from delivery costs, lending, customer acquisition, or management decisions.
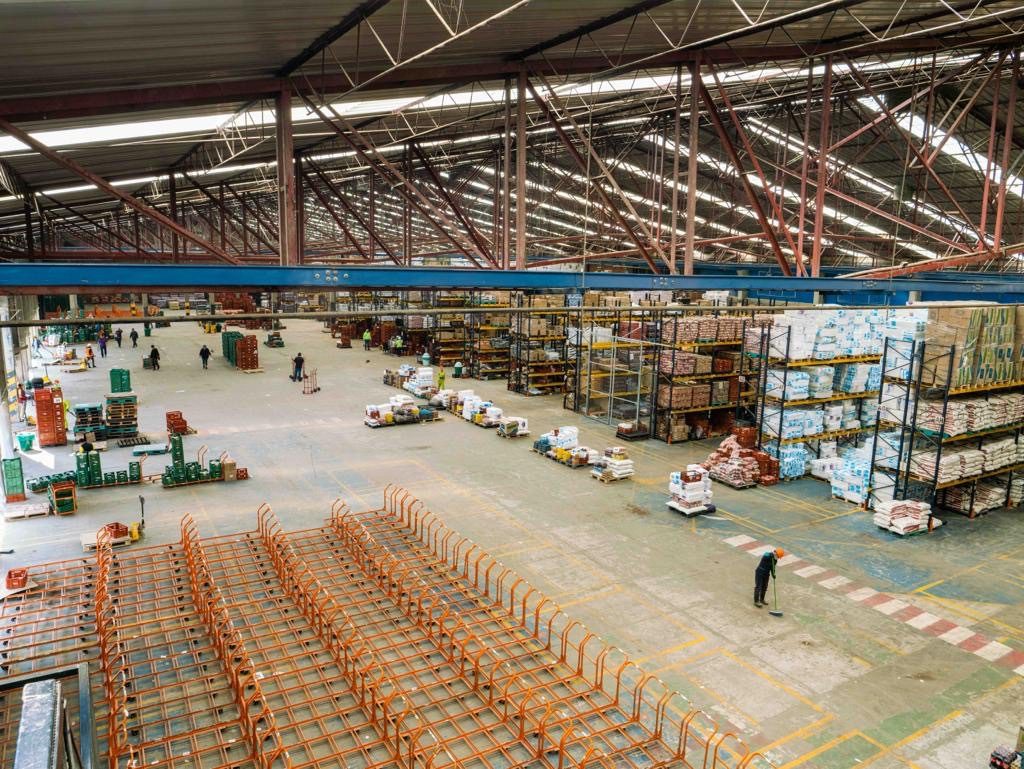
Image 1 / 1
Founding Story
Founder Fabián Gómez Gutiérrez previously worked at Rappi and McKinsey. He described the task as understanding demand and building tools for the food supply chain. His later explanation was concrete: perishable products deteriorate quickly, so predicting purchases and avoiding handling errors matters. [3]
Lightspeed partner Alex Taussig met Gómez in late 2019 and invested in the $65 million Series B announced in June 2021. The investor saw produce procurement as a recurring entry point into a larger wholesale basket. Restaurants could begin with fresh food and add proteins or packaged goods to the same delivery. This is a plausible distribution advantage: frequent essential purchases create repeated opportunities to sell other categories. It also makes reliable physical fulfillment part of the promise. [2]
Timeline
- 2018–2019: Founded in Colombia; joins YC Winter 2019. [1]
- October 2020: Enters Brazil, according to NeoFeed's retrospective. [7]
- June 2021: Announces a $65 million Series B with Lightspeed, GGV, Tiger, SoftBank, and Monashees. [2]
- June 2022: Says it cut less than 3% of Brazilian staff following a strategy change. [9]
- November 2022: Executives report more than $2 million disbursed in restaurant credit. [3]
- December 2023: Regional manager reports operating breakeven at the end of Q1 2023, with net profitability still a three-to-four-year aspiration. [4]
- February 2024: Suspends Colombia and Mexico; company statement says Brazil represents 60% of revenue. [5]
- March 2025: Accion announces a financing partnership with Frubana and Mastercard's Center for Inclusive Growth. [6]
- July 30, 2025: Final Brazil delivery, as the company's farewell was reproduced by Forbes and NeoFeed. [7][8]
What They Built
The service connected restaurant ordering to a mixed supply model. Lightspeed described directly purchased produce passing through regional distribution centers and planned delivery routes. Proteins and packaged goods also came through a third-party marketplace. That distinction matters: Frubana combined inventory handling with marketplace sales, rather than using one uniform ownership model for every category. [2]
Inside fulfillment, operations staff replaced tape and handwritten labels with stickers containing emoji and barcodes. Vice president of operations Andrés Sarmiento told Forbes that this reduced picking errors to 0.6%. The number is a company-reported process metric, not an independently measured margin improvement. Private labels Naoli and Moppy covered grains and cleaning supplies. [3]
Frupay added credit, payment processing, and business-management software. In March 2025, Accion reported 80,000 loans already issued and said alternative data helped credit decisions. Its release also described an intended reach of more than 200,000 small businesses; that was a partnership goal, not the number financed. The eight-year partnership referenced in the release was Accion's broader relationship with Mastercard, not eight years of Frubana lending. [6]
Market Position
Target Customers
Frubana targeted small restaurants and food businesses whose buyers had to coordinate stock, suppliers, prices, and deliveries. In December 2023, regional manager Gonzalo Vásquez reported approximately 100,000 customers across three countries. He described digital campaigns and an internal sales force as acquisition channels. These were company statements at that date, not a current customer count. [4]
Market Size
The opportunity depends on recurring procurement, but total food spend is not the revenue a platform can retain. A useful market model must separate goods sold, marketplace fees, advertising, and financial income. Public reports do not provide enough segment-level accounts to estimate Frubana's addressable profit or compare country contribution margins.
Competition
Wholesale markets and existing distributors remained alternatives to a unified app. Buyers could retain personal supplier relationships, negotiate directly, or avoid dependence on one platform. Frubana offered convenience and a broader basket, while taking responsibility for fulfillment.
Today, a supplier-connected rebuild also faces software overlap. Vendara advertises food-service quote comparison, purchase orders, and delivery discrepancy records. Inventa's merchant terms describe supplier-intermediated purchasing and installment payments subject to approval; its audience is retailers, so it is an adjacent financing model rather than an exact restaurant equivalent. Their product descriptions establish overlap, not customer traction or superior economics. [10][11]
Business Model
Regional management described two revenue sources in 2023: buying and reselling products, and Frubana Ads campaigns sold to suppliers. Financing could also encourage larger purchasing baskets through partner-funded loans. None of this establishes how much each activity contributed to profit. [4]
The physical operation had to fund purchases, stock handling, delivery, and customer service before the retained revenue could cover overhead. Lending added funding, servicing, and credit-risk questions. These are business requirements inferred from the documented activities; public accounts do not disclose the corresponding costs.
Funding bought time to build this system. NeoFeed reported a $75 million Series C in July 2022 followed by an undisclosed extension that December. Its cumulative $271 million figure covers seven rounds. [7]
Post-Mortem
Financing dependence survived operational improvements
Operating breakeven and net profitability measure different things. The 2023 management account left net profitability in the future. Two months after that interview was published, the company told Forbes it could not raise the resources needed to continue Colombia and Mexico. The company still needed outside capital after its reported operating progress. [4][5]
Concentration reduced the footprint but did not ensure survival
Brazil was selected because it represented 60% of revenue in the February 2024 statement. Revenue share alone does not establish which market produced the best cash contribution. Closing two countries could reduce obligations, but the remaining service still needed suppliers, fulfillment capacity, customers, and funding. [5]
NeoFeed reported that some staff were told a proposed $40 million investment did not materialize before the final closure. That is attributed reporting, not a verified term sheet or management response. The founder did not respond to the outlet before publication. It nevertheless fits the earlier company statement linking continued operations to fundraising. [7]
Credit was already part of the response
The March 2025 partnership shows that embedded finance was an active strategy before shutdown. It therefore cannot explain the outcome as an obvious missing feature. Accion's loan-volume claims demonstrate activity, but its qualitative delinquency assessment does not disclose portfolio losses, funding cost, or net income. Procurement data may help a lender evaluate customers; it does not guarantee that lending improves the platform's overall economics. [6]
The strongest alternative explanation would be viable local operations undermined by financing timing or legacy obligations. The public record lacks cash-flow and country-level accounts needed to test it. A rebuild should measure those dependencies directly instead of assuming that removing owned warehouses or adding credit solves them.
Key Lessons
- Use recurring purchasing to build distribution. Produce orders gave Frubana opportunities to sell a broader basket. Fulfillment quality remained essential to keeping that relationship. [2]
- Measure the whole cash requirement. A favorable operational milestone can coexist with financing needs. Include overhead, working capital, and financial obligations when deciding whether to expand. [4][5]
- Choose markets by contribution as well as revenue. Brazil's large revenue share justified attention, but public figures do not establish that concentration made the business self-funding. [5]
- Evaluate finance as a separate business. Frupay existed before shutdown. Loan volume and procurement data should be tested against servicing costs, losses, and contracted funding. [6]
Sources
- Y Combinator — Frubana company profile
- Lightspeed — Frubana investment thesis, June 2021
- Forbes Colombia — Frubana credit and warehouse operations, November 2022
- Valora Analitik — Interview with regional manager, December 2023
- Forbes Colombia — Company statement on Colombia and Mexico exits, February 2024
- Accion — Frubana and Mastercard financing partnership, March 2025
- NeoFeed — Brazil closure, July 2025
- Forbes Colombia — Final delivery and closure, August 2025
- Bloomberg Línea — Frubana staff cuts, June 2022
- Vendara — Current food-service procurement offering
- Inventa — Merchant purchasing and credit terms