Momence
Summer 2020AcquiredScheduling and payments for experiences
Pressure-test this opportunity
Explore the risks and possibilities with a prompt for ChatGPT, Claude, or your agent.
Scheduling and payments for experiences
Explore the risks and possibilities with a prompt for ChatGPT, Claude, or your agent.
Momence began in 2020 as Ribbon, a checkout and operations layer for instructors forced onto Zoom. It became a broad system for boutique fitness and wellness businesses: scheduling, memberships, payments, messaging, marketing, staff, retail, video, and reporting. By January 2025, the company said more than 4,500 businesses used the product and hundreds of thousands of consumers booked through it each month.[1]
Clubessential Holdings acquired Momence on January 29, 2025. The parties did not disclose the price. Momence remained active inside Clubessential's fitness portfolio, then became part of Xplor Technologies when Xplor and Clubessential completed their merger in March 2026.[2]
Momence combined a narrow customer relationship, embedded payments, and an unusually broad operating product. That made a lightly funded startup useful to an acquirer assembling vertical software and payment volume. The acquisition was a successful exit, and the product continues under Xplor.
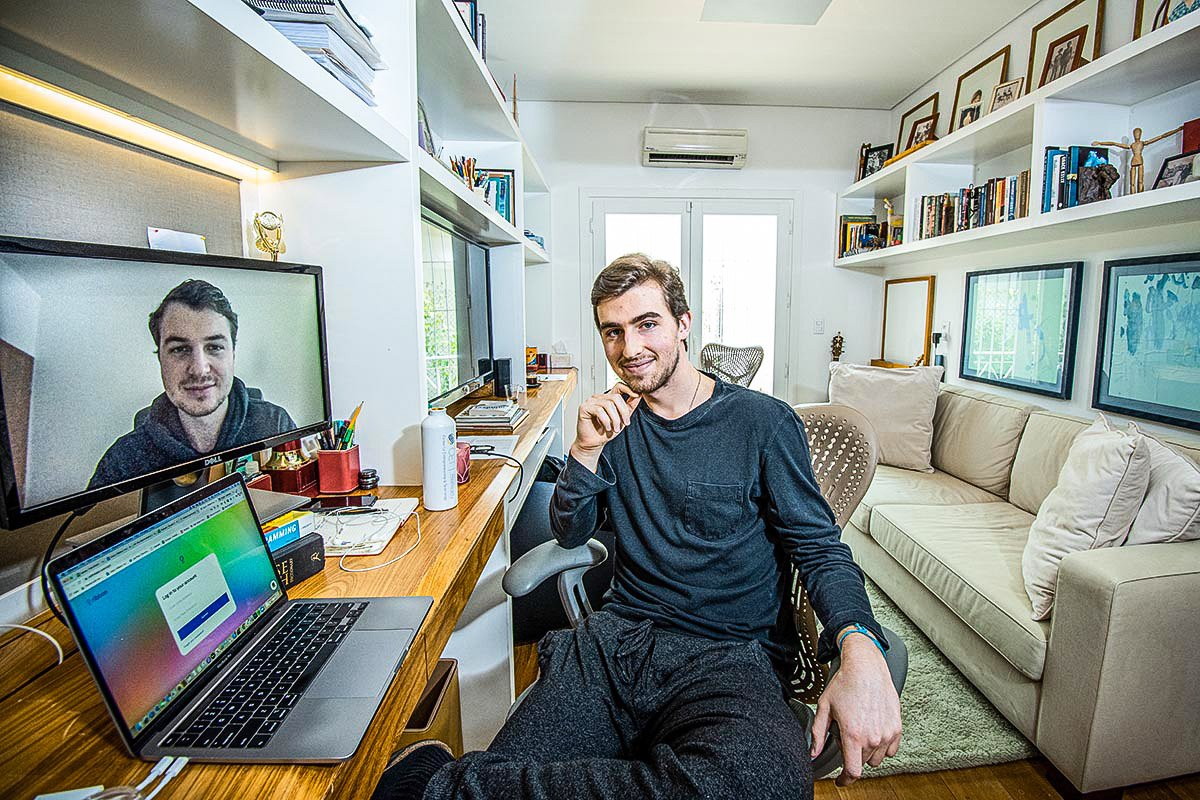
Image 1 / 2
Vojta Drmota and Matteo Carroll met while playing soccer at Harvard. Carroll, from Brazil, graduated in 2019; Drmota, who grew up in Sweden and has Czech roots, studied philosophy and computer science and graduated in 2020.[3] They had already experimented with payments. A third Harvard student joined them on Lux Pay, a finger-vein payment system tested at a Harvard Square convenience store. Roughly 210 students registered, but Apple Pay and Google Pay offered a simpler path for most merchants and consumers.[4]
The COVID-19 lockdown supplied a more urgent problem. Carroll returned to Brazil and Drmota to the Czech Republic. In April 2020, they watched yoga teachers, fitness instructors, and other independent hosts move classes onto Instagram and Zoom without a way to sell access, collect recurring payments, track customers, or send reminders. They built and launched Ribbon Experiences in less than two months.
Carroll told Exame, in Portuguese, “Mas não tinha nada para organizar isso, e muitas vezes era difícil fazer a venda propriamente, cobrar e acompanhar pagamentos.” The gap was commercial rather than video delivery: Zoom carried the class, while Ribbon handled the sale and the customer record.[5]
The first product sold tickets and subscriptions, issued Zoom links, embedded checkout on the host's site, sent emails, and tracked customers and payments. A September 2020 company post described fixed-price and donation-based classes, customized reminders, and a basic CRM.[6]
The founders initially imagined geography becoming less relevant. Carroll said, “Quem gosta de yoga pode procurar mestres da Índia sem ter de viajar até lá.” Yet customers soon mixed online and physical classes. That behavior pointed toward a more durable product: the operating system for the host, regardless of where the experience happened.
Ribbon separated teaching from commerce. A host kept using Zoom or another video tool, then used Ribbon to create an event, set a fixed or donation price, issue tickets, sell memberships, and email registrants. Checkout could live on an existing site or on a generated host page. The product did not need to win video streaming to make the virtual class economically usable.
As physical venues reopened, the product followed the business rather than the channel. The 2021 Momence rename kept every link and plugin working, while the company widened the promise from online events to “moments and experiences.” Early investor ONEVC described live and recorded events, subscriptions, ticketing, video integrations, and email marketing for hosts ranging from yoga teachers to school instructors.[9]
The current product is much deeper. An operator can create classes and one-to-one appointments, sell packs and recurring memberships, assign instructors and rooms, collect online or point-of-sale payments, track arrival, manage retail inventory, and calculate payroll. The member app handles booking, credits, child accounts, payment methods, and studio messages. Momence deliberately limits discovery: members see the businesses they already visit instead of a marketplace that promotes competing studios.[10]
Marketing and retention sit beside operations. Studios can collect leads from websites and Facebook ads, run automated communication sequences, send email, SMS, in-app messages, and social direct messages, and trigger outreach when a class has an empty spot. The platform also supports on-demand video, teacher-training courses, reviews, intake forms, SOAP notes, workout programming, dance recitals, costume management, and multi-location reporting.
That breadth makes the all-in-one claim credible, but it also creates a large product surface. Momence's help center spans onboarding, payments, appointments, classes, subscriptions, marketing, franchise controls, AI sales tools, retail, reports, and troubleshooting.[11] A studio can replace several tools, while Momence must keep each workflow reliable enough to hold bookings and money.
The first customer was an individual instructor or creator selling online access. Momence narrowed toward owner-operated fitness and wellness businesses: yoga and Pilates studios, gyms, dance schools, spas, clinics, sports facilities, and later franchises. The buyer often runs the classes, manages staff, answers members, and reviews the merchant statement. Product speed and support therefore matter alongside enterprise controls.
The acquisition announcement positioned Momence as the system for independent fitness operators and contrasted its single-studio loyalty with multi-brand consumer marketplaces.[1] That boundary matters. Mindbody and ClassPass can deliver demand, but they also make competing venues visible. Momence sells a direct customer relationship under the studio's brand.
No observed source provides a neutral market estimate for studio-management software alone. The operating market is large enough to support several vendors. The Health & Fitness Association's 2025 benchmark covered 175 companies and more than 17,000 facilities across 27 countries. Respondents reported median 2024 revenue growth of 9.9%, 5.5% net membership growth, and 66.4% member retention.[12] These figures skew toward participating operators and are benchmarks, not Momence's addressable revenue.
Momence competes with Mindbody, Mariana Tek, Glofox, Zen Planner, PushPress, Vagaro, WellnessLiving, Gymdesk, bsport, Arketa, TeamUp, and modality-specific products. The key axes are operator depth, member experience, marketplace distribution, payment economics, and support for multiple locations.
Mindbody has the strongest consumer discovery brand and now starts at $79 per US location for its entry plan.[13] Mariana Tek targets premium multi-location boutiques. PushPress and Gymdesk lean toward gyms and martial arts. Smaller products compete on price and simplicity. Momence's advantage was an unusually wide feature set with a modern member experience and a free entry tier.
The same breadth weakens a greenfield clone. Scheduling, billing, marketing, and AI follow-up are already table stakes. Momence now sits inside Xplor beside ClubReady, Exerp, myFitApp, and Mariana Tek, backed by a company that serves more than 130,000 businesses and processes over $47 billion in annual payments.[2] A new entrant needs a narrower economic wedge than “all in one.”
Ribbon initially charged hosts a service fee on transactions. Momence kept transaction revenue and added subscriptions. Its current US pricing starts with a free Basic plan that charges 5% to the operator and 4% to the client, before standard payment processing. Pro costs $60 per month and charges the operator 2.5%. Custom starts at $199 per month with no Momence payment fee, though standard processing still applies.[14]
The model uses low software prices to acquire small studios, then earns more as their payment volume grows or as they need staff, locations, reporting, inbox, retail, and add-ons. It aligns revenue with customer activity, but a percentage fee can become more expensive than the subscription at scale.
Financial disclosure is limited. Exame reported a $1.2 million seed round in October 2020. Infrastructure partner Pipetail later said Momence raised $1.35 million in total and grew beyond $15 million in annual revenue with about 100 employees; those figures are vendor-published, not audited.[8] If accurate, they describe a capital-efficient vertical software company. The acquisition price, profitability, gross payment volume, retention, and founder or investor proceeds remain private.
Ribbon reached 950 creators in ten countries and more than 45,000 end users within months of launch, with little reported marketing spend. The company was already collecting service fees and described itself as profitable with only the founders working full time.[5]
By the 2025 acquisition, Momence reported more than 4,500 business customers and hundreds of thousands of monthly consumer bookings. Clubessential's combined fitness products served 15,000 locations, processed nearly $4 billion each year, and reached 13 million members.[1]
Pipetail's account says revenue was growing 35% year over year during the infrastructure work and exceeded $15 million annually. It also says the engineering team doubled and the AWS cutover avoided downtime. These are supplier claims, but they explain a problem that only appears after traction: the original DigitalOcean and Ansible stack no longer offered the database availability, deployment controls, and observability expected from a platform carrying live bookings and payments.
Ribbon launched into a temporary shock, but the founders chose a lasting job. Instructors needed Zoom in 2020; they needed checkout, memberships, customer records, and communication in any year. The founders kept the commercial layer and let video remain an integration.
When customers resumed in-person classes, Ribbon already supported the mixed model. The rename to Momence changed the category language without breaking links or forcing a migration. That continuity let the company escape the “virtual events” label that trapped many pandemic products.
The original pitch covered creators, school teachers, and almost anyone hosting an experience. Momence became more valuable after concentrating on studios, gyms, spas, and dance schools. A narrower market produced recurring, category-specific work: class credits, instructor substitutions, spot selection, waivers, payroll, retail, recitals, and failed membership payments.
This was a disciplined form of expansion. The feature list grew because one buyer wanted to run the whole venue in one system. Product breadth without customer focus becomes a bundle; here, the repeated buyer and shared payment record tied the modules together.
Momence's published subscription prices are low relative to its product surface. Transaction fees make that possible. Every class, membership, package, appointment, and retail sale can produce payment revenue in addition to software revenue.
That helps explain the buyer. Clubessential described itself as a SaaS and embedded-payments provider, reported nearly $4 billion of annual fitness payment volume, and added Momence beside several membership systems. The later Xplor merger created a company processing more than $47 billion annually. The inference is stronger than an “AI acquisition” story: Momence brought thousands of merchant relationships and their payment flow.
Clubessential singled out Momence's refusal to operate as a multi-brand discovery marketplace. Members only see studios they already use. That may reduce consumer acquisition compared with Mindbody or ClassPass, but it protects the studio's direct relationship and avoids placing a competitor beside every booking.
The decision aligned operator incentives with the software vendor. Momence could sell marketing and retention tools without also taxing discovery or steering members elsewhere. For an acquirer built around membership organizations, loyalty to one operator was a product advantage.
Momence grew on DigitalOcean, managed PostgreSQL, PM2, and Ansible. By 2023, the platform needed higher database availability, multi-region controls, preview environments, observability, and reliable rollback. Pipetail describes a multi-year move to AWS, Aurora PostgreSQL, Kubernetes, GitOps, and a streaming data stack.[8]
The early stack was not a mistake; it bought speed when two founders were proving a market. The migration became necessary because bookings and payments turned downtime into a revenue event for thousands of businesses. The lesson is to replace infrastructure when its operational risk exceeds the migration risk, not when the architecture stops looking fashionable.
Momence did not disappear after January 2025. Its site, pricing, help center, hiring page, and product releases remain active. Clubessential merged into Xplor in March 2026, and Xplor's corporate history still lists Momence as an operating acquisition.[15]
Terms were undisclosed, so the evidence cannot establish investor returns or whether the price rewarded the reported revenue multiple. It does establish a founder exit, product continuity, and a second layer of consolidation. Momence now competes inside a portfolio that owns several adjacent systems, which may improve investment capacity while making product overlap and customer migration strategic questions for Xplor.