Overview
Simple built a banking interface around a useful question: how much money can I spend after setting aside my commitments? Founded in 2009, the company paired its software with a partner bank. BBVA agreed to buy it for $117 million in 2014. [1]
Its distinctive experience depended on another institution holding the accounts. That relationship supported product development, but also let the owner replace the interface while retaining the banking relationship. Simple closed in May 2021, before PNC completed its purchase of BBVA USA. The outcome supports a lesson about control of customer experience; public evidence does not isolate the app's standalone economics. [6] [7]
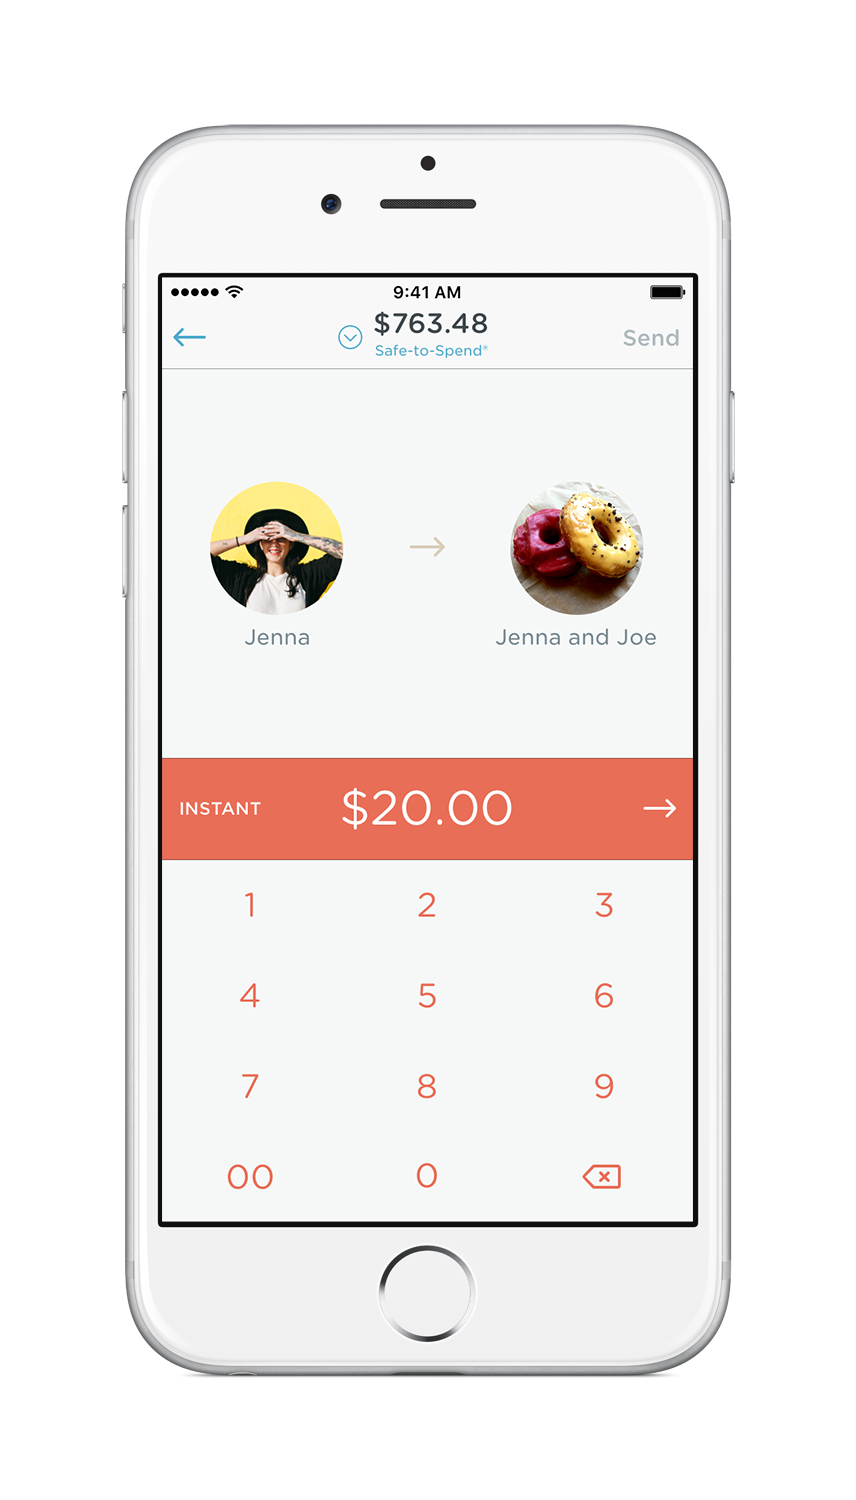
Image 1 / 1
Founding Story
Joshua Reich and Shamir Karkal met at Carnegie Mellon's Tepper School of Business. Karkal advised financial firms at McKinsey; Reich worked at Root Markets and in data consulting.
Observer reported a specific frustration in September 2009: Chase processed Reich's payments twice. Support transferred him between teams, and a later call found no record of his original complaint. The episode made confusing account information and service handoffs personal. [2]
Alex Payne joined from Twitter in 2010. He told Observer: “Coming from Twitter, where I built up their platform,” before explaining the work needed to help people understand platforms and products. The early team proposed a cleaner interface and bank partners to handle the underlying accounts. The initial vision included features that should not be mistaken for the eventual launch package. [2]
The attraction of an established banking owner was access to resources. In BBVA's February 2014 announcement, Reich said: “Joining with BBVA gives Simple the resources and global footprint we need to see our vision writ large.” The deal promised continued operation under the Simple brand. That promise describes the initial arrangement, rather than a permanent commitment to maintain the product. [1]
Timeline
- 2009: BankSimple was founded; its later Finovate profile gives October. [3]
- 2011: The company demonstrated at Finovate, reporting $13 million raised and 17 employees. [3]
- July 2012: Commercial launch, according to BBVA's acquisition announcement. [1]
- February 2014: BBVA announced its agreement to acquire Simple. [1]
- September 2016: Simple Shared entered beta. Access initially required accounts backed by BBVA Compass. [4]
- January 2021: Customers learned that Simple would close. [5]
- May 8, 2021: The Simple experience ended during account migration to BBVA USA. [6]
- June 1, 2021: PNC completed the separate acquisition of BBVA USA Bancshares, including BBVA USA. [7]
What They Built
Simple combined a debit card, mobile apps and spending tools. Its customer interface sat above the bank account; Simple itself was a technology company rather than the chartered bank. Bancorp was an early banking partner, followed by BBVA Compass. [1] [12] [4]
Safe-to-Spend and Goals made earmarked money visible in everyday decisions. Shared extended that idea to two people. Customers could maintain individual accounts alongside a shared account, with goals and spending visibility across the shared relationship. The transfer image captures that connection more clearly than a general promise of better banking. [4]
The bank connection constrained feature availability. Existing Bancorp customers needed to move to BBVA Compass before joining Shared's waitlist. A feature that looked like an app update therefore depended on moving the underlying account relationship. [4]
The shutdown also exposed how much behavior sat in the software. Customer transition instructions listed separate cutoffs for internal transfers, external transfers and mobile check deposits. Keeping the deposit account available did not preserve the customer's established workflow. [11]
Market Position
Target Customers
The product addressed people who wanted to manage spending through a phone, including pairs sharing expenses. Its Shared announcement explicitly included friends and other partnerships, beyond married couples. [4]
Market Size
Simple competed for an existing banking relationship. Counting all checking accounts would overstate demand for its particular budgeting approach. No reliable addressable revenue estimate or customer-level willingness-to-pay study was found.
Mobile banking later became routine. The FDIC's November 2024 release reported that 48.3% of banked households primarily accessed accounts through mobile banking in 2023. This measures access behavior, rather than demand for paid budgeting. [8]
Competition
Banks controlled account infrastructure and could distribute their own apps to existing depositors. Simple concentrated on the interface and customer experience. Those positions created a difficult dependence: the institution behind the product could also supply its replacement.
The central feature set remains available in independent software. As checked October 27, 2026, Beacon Budget, reached through the former DAS Budget domain, offers read-only bank connections, virtual buckets, joint budgets and a Free-to-Spend calculation. YNAB sells a broader planning method with account imports and household sharing. Neither should be represented as a continuation of Simple's company. [9] [10]
Business Model
Simple sought revenue from banking activity rather than a separate budgeting subscription. Founder coverage described lending and card transaction income. That early proposition does not establish its final revenue mix or margins. [2] [12]
Public sources reviewed here do not provide a consistent standalone revenue, contribution-margin or retention series. The purchase price cannot substitute for those measures. A budgeting feature can attract customers while the business still depends on deposit balances, card use, support costs and its agreement with the bank.
Traction
BBVA reported more than 100,000 customers at the 2014 announcement, five times the end-2012 base. That was evidence of adoption following launch, rather than a count of profitable accounts. [1]
The Shared announcement later reported 43% customer growth over six months without an absolute count or cohort economics. It documents continuing growth under BBVA, but cannot establish the eventual reason for closure. [4]
Outcome and evolution
Finextra reported BBVA's closure decision in January 2021. Reich's reproduced response began: “I don’t have any additional insight.” His suggestion about PNC prioritizing its technology was an outside hypothesis, not an insider account of the decision. [5]
The strongest explanation supported here is that the owner ended a separate customer interface during a wider transition. The evidence also permits an economic explanation: Simple may have lacked sufficient value to justify its continued cost. Standalone financial evidence is missing, so that alternative cannot be ranked confidently.
The migration had its own operational failures. Finextra documented enrollment and login errors and reproduced BBVA's apology. BBVA said debit cards and scheduled transactions remained unaffected. Loss of app access therefore must not be described as proof that deposits disappeared. [6]
As reviewed October 27, 2026, the historical Simple consumer service remains closed. PNC's completed acquisition concerns BBVA's US business; it does not establish that Simple's interface survived. [6] [7]
Key Lessons
- Simple made committed money part of the spending decision. Its Shared product extended that idea without requiring partners to surrender individual accounts. [4]
- Simple's bank partnership shaped product access. Requiring a bank migration before Shared demonstrates that backend ownership can determine a consumer feature's rollout. [4]
- Simple's acquisition preserved the brand initially, while later account migration ended the experience. Founders should examine who can retire the interface and what customers can export. [1] [11]
- Simple's migration problems distinguish account continuity from usable access. A transition needs tested enrollment and support, even when payments continue. [6]
Sources
- BBVA acquisition announcement
- Observer visits BankSimple founders
- FinovateFall 2011 BankSimple profile
- Simple Shared beta announcement
- Simple shuts down
- Simple migration login errors
- PNC completes BBVA USA acquisition
- FDIC household banking survey release
- Beacon Budget official product and pricing
- YNAB official pricing
- Simple transition dates reproduced by customer
- BBVA makes banking Simple