Overview
ReadyForZero was a San Francisco-based personal debt management platform founded in 2010 by Rod Ebrahimi and Ignacio Thayer. The company participated in Y Combinator's Summer 2010 batch, raised approximately $4.8 million in venture funding, and built a product that helped consumers aggregate their debts, visualize payoff progress, and automate payments. By the time of its acquisition in March 2015, the platform had helped users pay down over $220 million in debt and had signed up roughly 250,000 users.[1][13]
ReadyForZero failed because it built a debt-management tool that users loved but wouldn't pay for at scale. Only 4% of its quarter-million users upgraded to premium services, and the company was forced to shut down its paid offerings in early 2015 due to insufficient resources to maintain them.[15] The pivot to a B2B2C API model and ambitions to enter lending came too late to save the standalone business. Avant acquired the company as a talent and product acquisition, then quietly shut down its tools eighteen months later when they proved redundant with Avant's own lending operations.
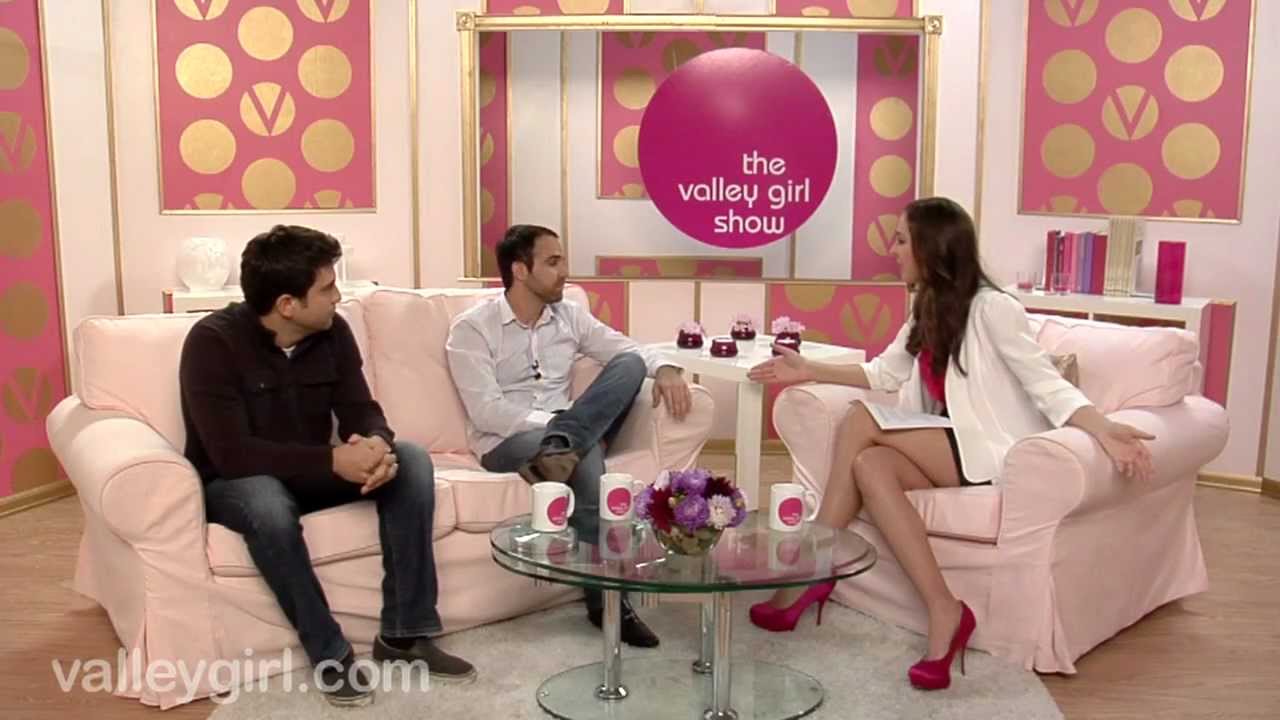
Image 1 / 2
Founding Story
ReadyForZero was founded in 2010 by Rod Ebrahimi (CEO) and Ignacio Thayer (CTO), two engineers who met through their shared technical background. Thayer was a former senior software engineer at Google before co-founding the company.[29] Ebrahimi, who had previously worked in technology and finance, brought the founding insight — one that came not from market research but from a personal relationship.
The idea emerged from a specific moment: Ebrahimi's girlfriend asked him and his tech friends, "Where do I go to manage all my debt?" — and none of them had an answer.[2] She carried six-figure debt, and the scale of the number itself was paralyzing. Ebrahimi recognized that the psychological barrier — not just the financial one — was the real obstacle. He told Y Combinator's blog: "I know it seems very small, but just seeing (her debt) visually going down helped. And we provide that. She was in the six-figure range in total, so just seeing that number didn't motivate her to pay it down. (She) just felt like, I can't do it. ReadyForZero made it a little more tangible."[3]
The founders had originally planned a news-aggregating service for Y Combinator's Summer 2010 batch, but pivoted to the debt-relief concept during the incubator program itself.[2] This pivot was enabled by YC's initial $17,000 seed investment.[4] The company then raised a $260,000 seed round in October 2010 from a notable angel group including Steve Chen (YouTube co-founder), Dave McClure, Benjamin Ling, Nils Johnson, and Maneesh Arora.[5]
The founding vision was deliberately modest: provide tools for consumers to get control of their debt on their own, not to take over management of the debt.[8] This positioning — empowerment rather than intermediation — would shape both the product's appeal and its commercial limitations.
Timeline
- June 2010: Founded by Rod Ebrahimi and Ignacio Thayer; participated in Y Combinator S10 with a $17,000 seed investment.[1][4]
- October 2010: Raised $260,000 seed round from angels including Steve Chen and Dave McClure.[5]
- February 2011: Launched publicly.[7]
- June 2011: Raised $4.5M Series A led by Polaris Venture Partners with Citi Ventures; total funding reached ~$4.8M.[6]
- September 2011: Presented at FinovateFall 2011 in New York.[26]
- April 2012: Featured in NBC News; product described as collecting credentials to manage debt.[8]
- September 2013: Student-loan debt became fastest-growing segment; $250M of $1B total debt under management.[9]
- June 2014: Launched API for B2B2C partnerships.[10]
- Early 2015: Shut down paid services due to lack of resources to maintain them.[16]
- March 31, 2015: Acquired by Avant in cash and stock deal; co-founders moved to Avant's LA office.[13][19]
- November 2016: Avant shut down ReadyForZero's credit score and debt planner tools, deactivating user accounts.[21]
What They Built
ReadyForZero was a web-based debt management platform that connected directly to users' financial accounts. The core product collected users' account credentials to access balance and payment information directly from credit card companies, loan servicers, and mortgage holders, then aggregated that data into a single dashboard.[8] This was the product's central value proposition: instead of logging into five different portals to understand their financial position, users could see everything in one place.
The platform's signature feature was its pay-down recommendation engine. Based on the aggregated debt data, ReadyForZero calculated the optimal order and amount for paying down each debt — typically using the "avalanche" method (highest interest rate first) or the "snowball" method (smallest balance first) — and presented users with a personalized payoff plan. The visual representation of debt decreasing over time was a deliberate design choice, rooted in Ebrahimi's observation that his girlfriend found the sheer scale of her debt paralyzing rather than motivating.[3]
The service was free at its core, with paid premium options providing features such as credit monitoring and automation.[30] The premium tier cost $7 per month and included scheduling and making payments on loans automatically.[9] This freemium model was designed to convert engaged free users into paying customers over time.
The product evolved significantly over its five-year life. Initially focused on credit card debt, the platform expanded to handle student loans, which became its fastest-growing segment — by September 2013, student-loan debt represented $250 million of approximately $1 billion in total debt under management.[9] The company built data partnerships with Yodlee and Experian, and established lending partnerships with both Lending Club and Prosper.[11]
In June 2014, ReadyForZero launched an API to allow partners to deploy its debt-management tools on their own websites, marking a strategic shift from a B2C business toward a B2B2C model. The goal was to make the tools available on the sites of major financial institutions.[10] This pivot acknowledged the fundamental challenge of the B2C model: acquiring users directly was expensive, and the company's tools were arguably more valuable as an embedded feature within institutions that already had customer relationships.
The product earned significant recognition. It was named one of TIME's 50 Best Websites of 2014 and was featured on The Today Show, CNNMoney, Forbes, Mashable, and The Economist.[12] According to Avant's press release, the product was proven to reduce net-credit losses at top U.S. banks and helped consumers with subprime credit raise their FICO Score by as much as 40 points.[27]
Market Position
Target Customers
ReadyForZero targeted American consumers carrying credit card, student loan, and other consumer debt. The product's core demographic was middle-class households with multiple debt obligations — people who had the income to pay down debt but lacked a systematic approach. The student-loan segment, which became the fastest-growing portion of the business, skewed younger and included recent graduates managing their first significant financial obligations.[9]
Market Size
The addressable market was enormous. American consumer debt exceeded $1 trillion in credit card and student loan obligations during ReadyForZero's operating years, with student loan debt alone surpassing $1 trillion nationally in 2012. The company's own traction — $1 billion in total debt under management by 2013 — represented a fraction of a percent of the total market.[9] The market was large enough that market size was never the constraint; the challenge was converting awareness into sustained engagement and, crucially, into revenue.
Competition
ReadyForZero operated in a competitive landscape that shifted dramatically over its five-year life. The company's early competitors were primarily other debt-management startups and traditional credit counseling services. Mint.com, acquired by Intuit in 2009, was the most prominent adjacent product — it aggregated financial accounts and provided budgeting tools, though it did not focus specifically on debt payoff strategies. Credit counseling nonprofits like the National Foundation for Credit Counseling offered debt management plans but required users to cede control of their accounts.
The competitive dynamics changed in two significant ways. First, the major credit bureaus and financial data aggregators began moving into the space. Experian, which partnered with ReadyForZero for data, also launched its own consumer-facing credit monitoring products. Second, and more consequentially, the rise of marketplace lenders like Lending Club and Prosper — both of which partnered with ReadyForZero — created a structural tension. These lenders had a natural incentive to originate new loans rather than help consumers pay down existing ones. A debt-payoff tool was, in some sense, the opposite of a lending business: it reduced the pool of potential borrowers.
The most important competitive threat was the one that ultimately acquired the company. Avant (formerly AvantCredit), a Chicago-based online lender, had raised $334 million in equity capital and nearly a billion in debt financing by March 2015, and had issued over 150,000 loans.[31] Avant's core business was originating consumer loans — a model that required exactly the kind of credit data and consumer engagement that ReadyForZero's tools generated. The acquisition was less a merger of equals than an absorption of a complementary asset into a much larger machine.
Structurally, ReadyForZero was competing on a dimension where incumbents had a natural advantage. The company's product was a feature — debt aggregation and payoff planning — that could be (and eventually was) absorbed by larger platforms with existing distribution. Mint had the distribution through Intuit. The credit bureaus had the data. The lenders had the capital. ReadyForZero had the best standalone product, but standalone products in fintech rarely survive without a proprietary distribution channel or a regulatory moat.
Business Model
ReadyForZero operated a freemium model. The core service — debt aggregation, payoff planning, and progress tracking — was free. Premium features, including automated bill payment and credit monitoring, cost $7 per month.[9][30]
The company never disclosed its revenue figures, and the absence of revenue data is itself a signal. At the time of acquisition, TechCrunch reported that just 4% of the company's roughly 250,000 users were upgrading to premium products.[15] That implies approximately 10,000 paying users. At $7 per month, that would generate roughly $70,000 in monthly recurring revenue, or approximately $840,000 annually — before churn, payment processing fees, and the cost of maintaining the premium infrastructure.
The unit economics were structurally challenging. The company had raised approximately $4.8 million in total funding[6] and maintained a peak team of 12 people.[28] A reasonable inference, given typical Silicon Valley burn rates for a 12-person engineering-heavy team in San Francisco, is that the company was burning between $1.5 million and $2.5 million annually — meaning the $4.8 million raised would fund roughly two to three years of operations. The company operated for nearly five years before acquisition, which suggests either lower burn than typical or additional revenue that was never disclosed. Either way, the 4% premium conversion rate was insufficient to build a sustainable standalone business.
The B2B2C API pivot in June 2014 was an attempt to find a more scalable revenue model — licensing the technology to financial institutions rather than relying on consumer subscriptions.[10] But the company had to shut down its paid services in early 2015, with Ebrahimi admitting: "We had misjudged how many people it would take to actually service that."[16]
Traction
ReadyForZero's traction metrics tell a story of genuine product-market fit undermined by a broken revenue model. Within four months of its February 2011 public launch, the platform had helped users eliminate $42 million in credit card debt, with regular users paying down debt 2x faster than the average consumer.[7]
By September 2013, the company had approximately $1 billion in total debt under management, with student-loan debt as the fastest-growing segment at $250 million.[9] At the time of acquisition in March 2015, the company had helped consumers pay down between $220 million and $250 million in debt (sources vary), and had signed up just over a quarter of a million users.[14][15]
The product's impact was real and measurable. Avant's press release claimed the product reduced net-credit losses at top U.S. banks and helped consumers with subprime credit raise their FICO scores by as much as 40 points.[27] The company's recognition — TIME 50 Best Websites, Finovate alum, features on The Today Show and in Forbes — reflected genuine consumer enthusiasm.[12]
But the conversion gap was fatal. A quarter-million users with $220 million in debt eliminated is a product that works. Four percent premium conversion is a business that doesn't. The company's own founder had articulated the principle that would prove its undoing: "The only validation a young company needs are people (ideally paying customers) who are using what the company creates and, even more importantly, people who believe they can't live without what the company creates."[24] By that standard, ReadyForZero had users who loved the product but not enough who believed they couldn't live without it.
Post-Mortem
The 4% Conversion Ceiling: A Product People Loved But Wouldn't Pay For
The primary cause of ReadyForZero's failure was the fundamental mismatch between the product's value proposition and its revenue model. The company built a tool that users engaged with deeply — 250,000 users, $220 million in debt eliminated, 2x faster payoff rates — but only 4% upgraded to the $7/month premium tier.[15]
This was not a failure of execution but a structural feature of the category. Debt management is a "negative motivation" product: users engage with it because they want to escape a bad situation, not because they derive ongoing pleasure from the service. The moment a user's debt is paid off — the product's ultimate success — they churn. The moment a user feels overwhelmed and stops engaging — the product's most common failure mode — they also churn. The product's success and its revenue model were in direct tension.
The team's attempt to address this was the premium tier itself: automated bill payment and credit monitoring were designed to create ongoing utility beyond the payoff journey. But the 4% conversion rate suggests that users either didn't perceive enough incremental value in automation, or that the population most in need of debt management was precisely the population least able to pay $7/month. Ebrahimi's own reflection — "We had misjudged how many people it would take to actually service that"[16] — points to a resource constraint, but the deeper issue was that even with adequate resources, the revenue per user was too low to sustain the cost of servicing them.
The B2B2C Pivot: Right Direction, Too Late
By June 2014, the company recognized the B2C model was not working and launched an API to let partners deploy its debt-management tools on their own websites.[10] This was a sound strategic move — the tools were demonstrably effective, and embedding them within financial institutions' existing customer relationships could have solved both the distribution problem and the willingness-to-pay problem (institutions would pay for the tools as a customer retention feature, rather than consumers paying for them directly).
But the pivot came four years after founding, with a team of 12 and approximately $4.8 million in total funding.[6][28] Enterprise sales cycles in financial services are measured in years, not months. The company did not have the runway to see the B2B2C model through. By early 2015, it had already shut down its paid services, unable to maintain them.[16]
The Structural Problem: A Feature, Not a Company
The non-obvious structural mechanism in ReadyForZero's failure is that the company built a feature that incumbents could absorb, and the incumbents did exactly that. Debt aggregation and payoff planning is a natural extension of three existing businesses: credit bureaus (who have the data), financial aggregators like Yodlee (who have the connections), and lenders (who have the customer relationships and the capital). ReadyForZero's partnerships with Yodlee, Experian, Lending Club, and Prosper[11] were both a validation of the product and a signal of its vulnerability — the company was building on infrastructure owned by potential competitors.
The acquisition by Avant illustrates this dynamic perfectly. Avant was a lender with $334 million in equity capital and nearly a billion in debt financing.[31] ReadyForZero's tools — which helped consumers understand and manage their debt — were valuable to Avant not as a standalone product but as a customer acquisition and engagement mechanism for its lending business. Avant CEO Al Goldstein framed it in mission terms: "It opens up our mission and our vision to a broader set of consumers. We want to offer better access to credit for the middle class."[20]
The shutdown eighteen months later confirms the analysis. Avant deactivated ReadyForZero's credit score and debt planner tools in November 2016, telling users: "While we will continue to provide you with plenty of informational content, effective November 12, 2016, ReadyForZero will be shutting down its credit score and debt planner tools."[21] The tools were redundant with Avant's own offerings or not core to its lending strategy. Ignacio Thayer confirmed on Facebook that neither he nor Ebrahimi were affiliated with the company anymore, adding: "Your concern and passion about ReadyForZero are evident which is good to see. Hopefully ReadyForZero did some good while it was alive."[22]
The Counter-Narrative: Was the Acquisition Actually a Success?
A contrarian reading of ReadyForZero's story is that the acquisition was a reasonable outcome, not a failure. The company raised $4.8 million, operated for five years, built a product that demonstrably helped hundreds of thousands of people, and exited via acquisition. The founders moved to Avant's Playa Vista office to lead engineering and product management, and Avant planned to hire 80-100 new employees in Los Angeles.[19] For a company that had essentially run out of options in its standalone form, an acqui-hire with product assets was a soft landing.
But this framing obscures the deeper problem. The acquisition was not a strategic merger that created value; it was an absorption that ended with the product being shut down. The founders were gone from the company within eighteen months. The users who had trusted ReadyForZero with their financial data had their accounts deactivated. The product that had helped eliminate $220 million in debt was discontinued. By the standard Ebrahimi himself articulated — that paying customers are the only validation that matters[24] — ReadyForZero never achieved validation at scale.
The Industry-Level Explanation
ReadyForZero's failure also reflects a broader pattern in fintech during the 2010-2015 period. The consumer fintech wave of that era produced many products that were genuinely useful but commercially unsustainable: Mint (before its Intuit acquisition), LearnVest (acquired by Northwestern Mutual in 2015), and numerous others. The structural problem was that consumer financial tools faced a "willingness-to-pay gap": the people who most needed help managing their finances were the least able to pay for it, and the people who could afford to pay often didn't need the help. This gap was eventually bridged by business models that monetized the data or the customer relationship rather than the tool itself — which is precisely what Avant did with ReadyForZero's assets.
The company's fundraising difficulty, which Ebrahimi described candidly — "Believe it or not, you go around [to investors] and say that people have debt in America, and some of them are like, They do? One investor said his house was paid for and he couldn't understand why people have debt. That was the wrong guy."[25] — was an early signal of the category's structural challenge. The investors who funded consumer fintech were often people who had never experienced the problem the products solved, and the products themselves had no obvious path to the returns those investors expected.
Key Lessons
ReadyForZero's 4% premium conversion rate demonstrates that engagement is not the same as willingness to pay. The company had 250,000 users who eliminated $220 million in debt — a product that clearly worked. But only 4% paid for premium features. For consumer fintech products addressing "negative motivation" (escaping debt), the revenue model must be designed from day one around the reality that the most engaged users are often the least able to pay. ReadyForZero's freemium model was a bet that engagement would convert to revenue; it didn't.
The B2B2C pivot was strategically correct but executed too late. ReadyForZero launched its API in June 2014, four years after founding, when the company had roughly $4.8 million in total funding and a 12-person team. Enterprise sales cycles in financial services run 12-24 months; the company didn't have the runway to see the model through. A pivot that might have saved the company in 2012 was merely a prelude to acquisition in 2014.
Building on partner infrastructure creates existential dependency. ReadyForZero relied on Yodlee for data aggregation, Experian for credit data, and Lending Club and Prosper for lending partnerships.[11] These partners were also potential competitors — and the company that eventually acquired ReadyForZero, Avant, was in the same category as its lending partners. When your partners can absorb your product, your standalone existence depends on being more valuable to them as a partner than as an acquisition.
The "feature, not a company" problem is fatal in fintech. ReadyForZero built an excellent debt-management feature. But debt aggregation and payoff planning is a natural extension of credit bureaus, aggregators, and lenders — businesses with proprietary data, distribution, or capital. A standalone company competing on product quality alone, without a proprietary data moat or distribution channel, faces structural headwinds that no amount of product excellence can overcome. The acquisition by Avant and subsequent shutdown was the market confirming that ReadyForZero's tools were worth more as a feature of a larger lending operation than as a standalone business.
Sources
- Y Combinator — ReadyForZero company page
- NBC News — ReadyForZero profile (April 2012)
- Y Combinator Blog — ReadyForZero founder interview (September 2013)
- PR Newswire — ReadyForZero Series A announcement (June 2011)
- TechCrunch — ReadyForZero seed round (October 2010)
- TechCrunch — ReadyForZero Series A (June 2011)
- TechCrunch — ReadyForZero funding and traction (June 2011)
- NBC News — ReadyForZero product description (April 2012)
- Y Combinator Blog — ReadyForZero student loan segment (September 2013)
- TechCrunch — ReadyForZero API launch (June 2014)
- Finovate — ReadyForZero acquired by Avant (March 2015)
- Avant Press Release — ReadyForZero acquisition (March 2015)
- TechCrunch — Avant acquires ReadyForZero (March 2015)
- Avant Press Release — Debt paid down figures (March 2015)
- TechCrunch — Premium conversion rate (March 2015)
- TechCrunch — Ebrahimi quote on paid services shutdown (March 2015)
- TechCrunch — Lending ambitions (March 2015)
- Avant Press Release — YC classmates detail (March 2015)
- Built In Chicago — Avant rebrands, acquires ReadyForZero (March 2015)
- Built In Chicago — Al Goldstein quote (March 2015)
- Crowdfund Insider — Avant shuts down ReadyForZero (November 2016)
- Crowdfund Insider — Thayer Facebook statement (November 2016)
- Crowdfund Insider — Founders no longer affiliated (November 2016)
- Fast Company — Ebrahimi essay on validation (August 2011)
- NBC News — Ebrahimi on fundraising difficulty (April 2012)
- Finovate — FinovateFall 2011 alum
- Avant Press Release — FICO score improvement claims (March 2015)
- Y Combinator — Team size and headquarters
- NBC News — Thayer Google background (April 2012)
- Finovate — Freemium model description (March 2015)
- TechCrunch — Avant funding and loan volume (March 2015)